Rat-infested property is “suitable for use as a dwelling”
The First-tier Tribunal has found that a property in disrepair, inhabited by rodents, is still suitable for use as a dwelling for tax purposes. This sounds illogical - so what’s the full story?
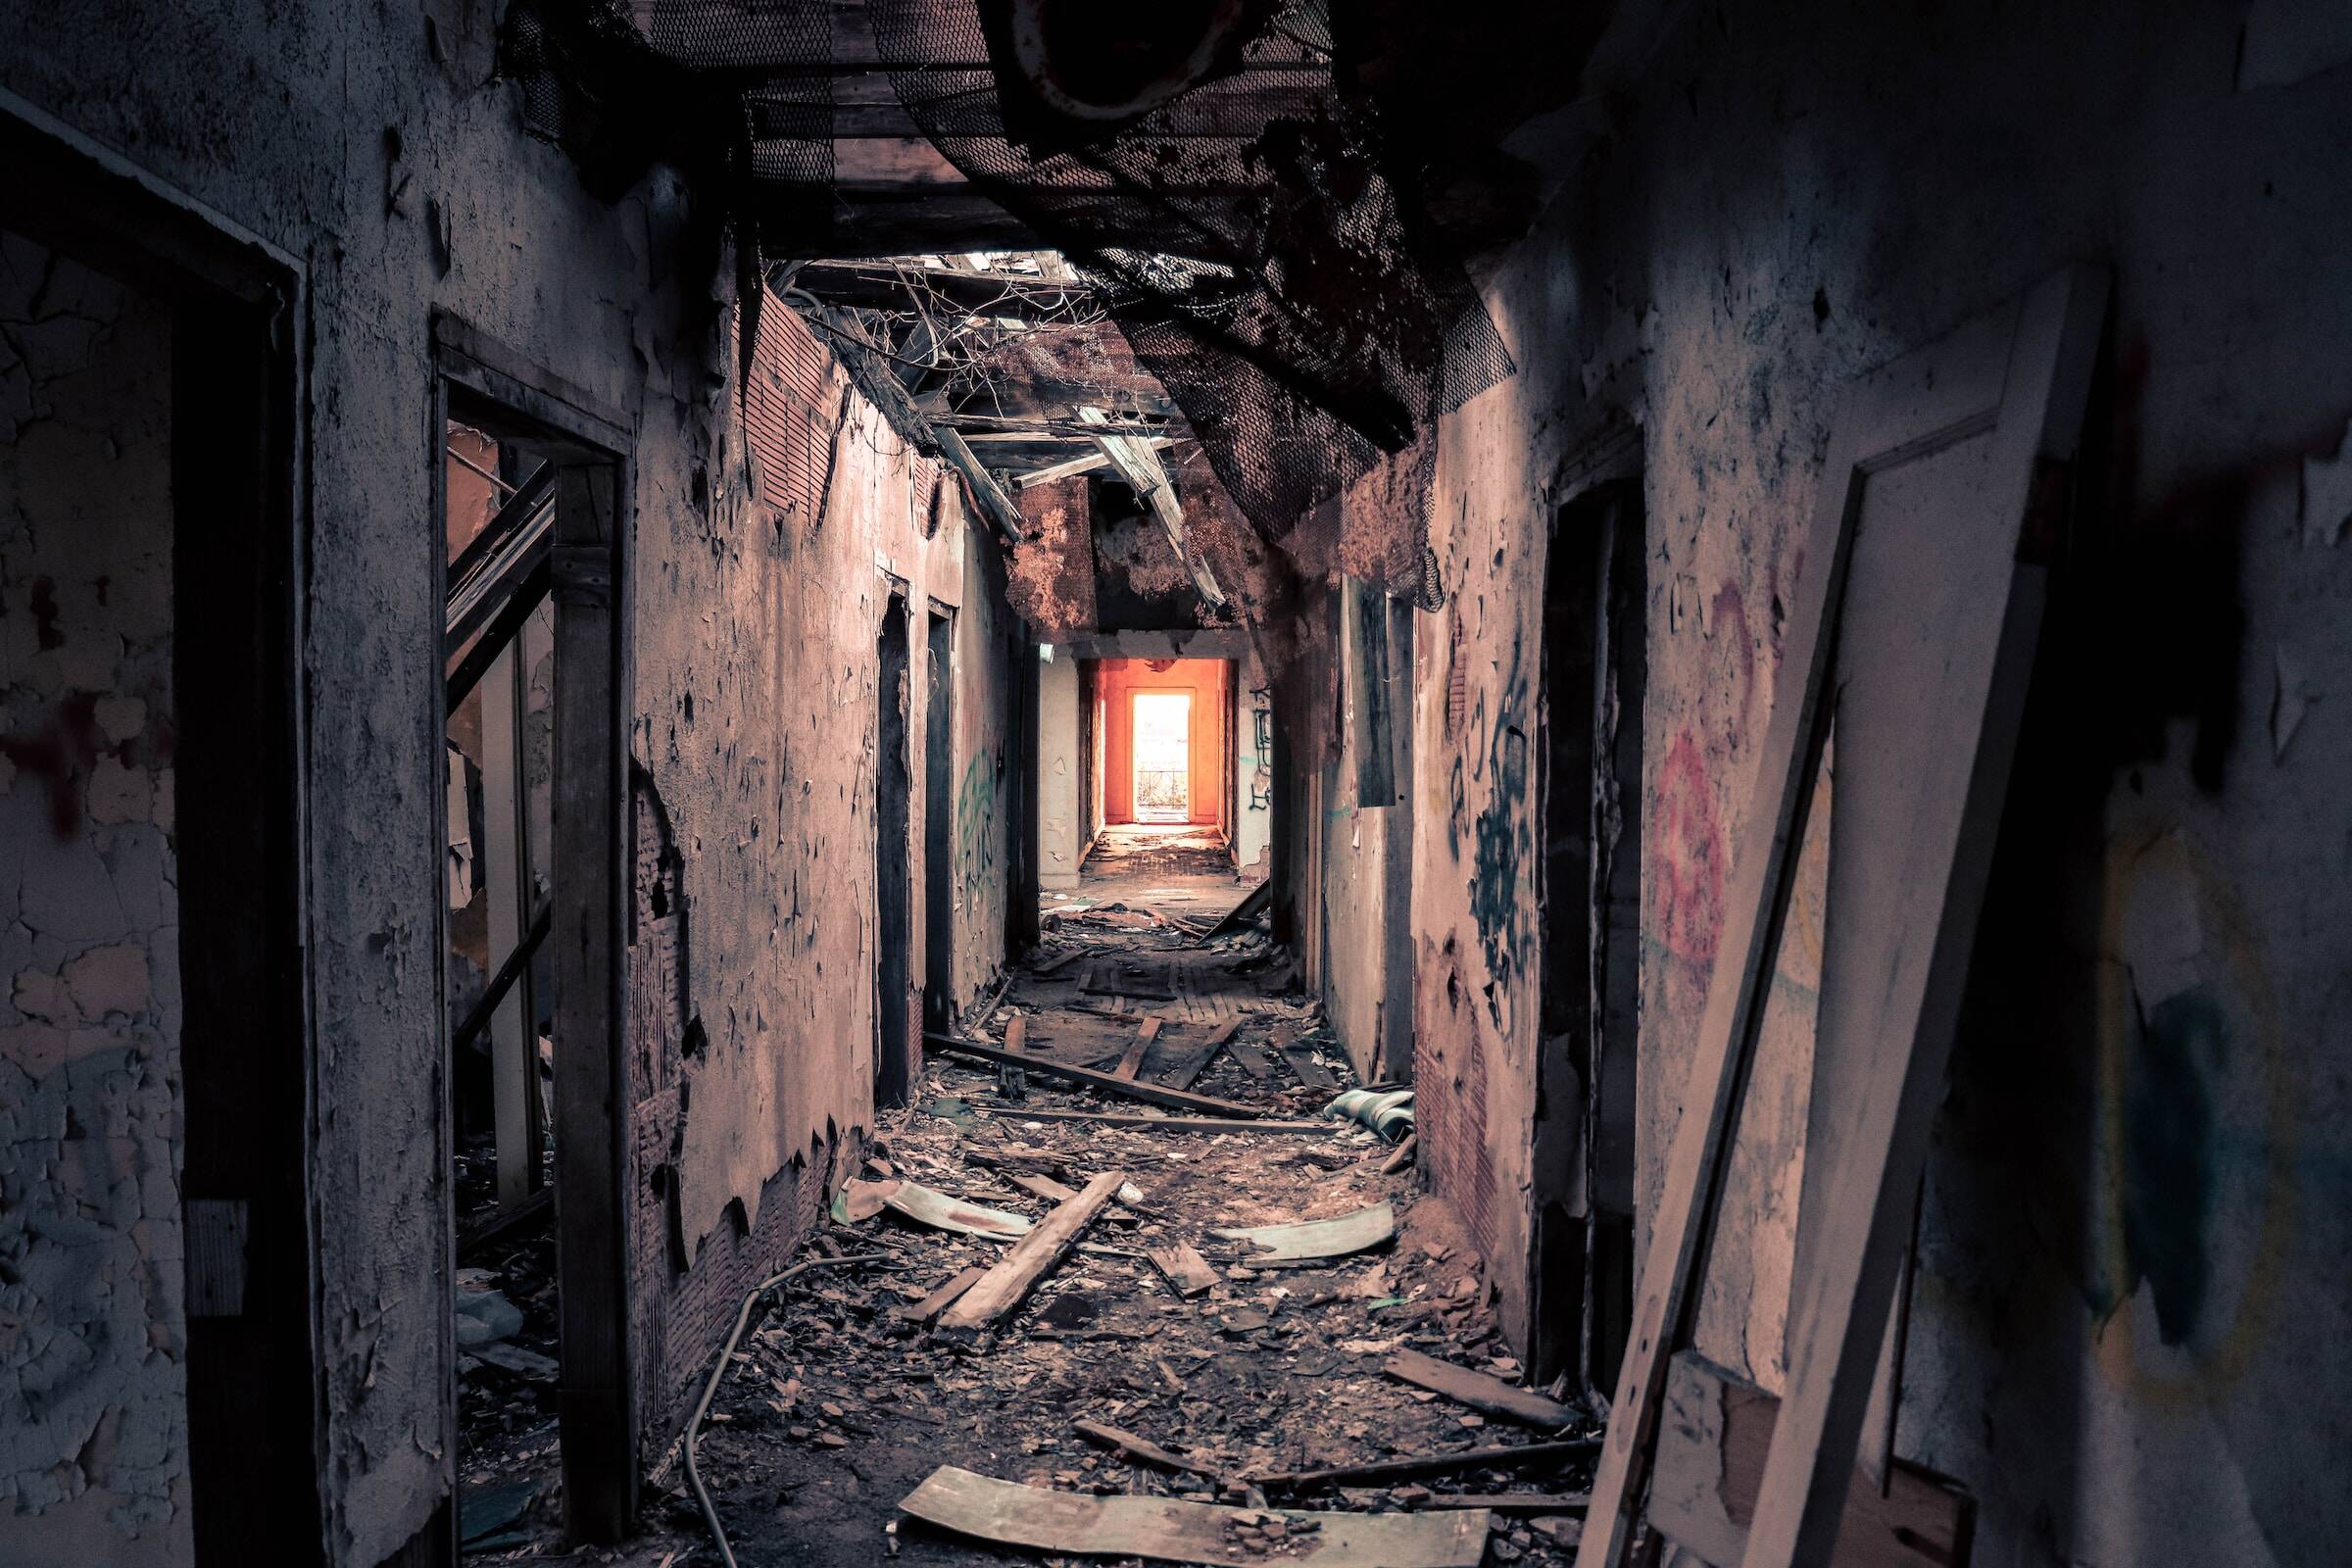
In Mudan & Anor v HMRC the taxpayers (the Ms) purchased a £1.7m property in London that had been empty for five months after the previous tenants were evicted. During that time, the property had been broken into and vandalised, none of the utilities worked and mice and rat droppings covered the kitchen. The boiler had been ripped off the wall, the gas, electricity and water were not functioning safely and rainwater was leaking into the property. It took nine months of renovations before the Ms moved into the property.
Higher rates of stamp duty land tax (SDLT) are chargeable on residential properties, with the pertinent part of the definition being that the property is residential if it is “suitable for use as a dwelling”. Due to the state of the property, the Ms argued that it was not suitable to be occupied and so lower rates of SDLT should apply. HMRC, and ultimately, the tribunal disagreed. The judge confirmed that the bar for a property not to be suitable for use as a dwelling was set very high, and that a building which was recently used as a dwelling, has not in the interim been adapted for another use, and is capable of being so used again will count as a dwelling for SDLT purposes. An additional £100,000 SDLT was due on the purchase, and the appeal was dismissed.
Related Topics
-
Why is HMRC checking PVA more often?
Your business imports goods and accounts for VAT by applying postponed VAT accounting (PVA) on its returns. HMRC is scrutinising returns and issuing large assessments in some cases. What can you do to reduce the risk of getting it wrong?
-
HMRC text or scam? Check before you act
HMRC is contacting some taxpayers by text this week about overdue Self Assessment liabilities and is also sending updates about VAT registration applications. At the same time, it has expanded its guidance on spotting fake HMRC messages on social media. How can you tell whether a message is genuine?
-
Electronic VAT return and payment due